Same mortgage payment. Paid off in 5–7 years. Wealth building starts now.
What if the money you already send the bank every month could pay off your home in a fraction of the time, then keep working to build your wealth and your retirement?
Results vary by household. The 5–7 year figure reflects Truth In Equity client averages and is not a guarantee.
Watch first: 4 minutes on how to stop paying the bank and start paying yourself.
How long it can take to pay off a home loan
Illustrative comparison. Your timeline depends on your income, expenses, loan, and equity.
Your mortgage was designed to take its time.
In the early years of a 30-year loan, most of each payment goes to interest instead of your balance. You can make every payment on time for years and barely move the number you owe.
It is not your fault, and it is not something you did wrong. It is how the loan is built. The good news is there are ways to change how your money moves so far less of it goes to the bank.
Your dollars, working harder.
Credit Line Banking changes how your existing income flows through your accounts, so less of it sits idle and less of it goes to interest.
- 1
Free analysis
We look at your real mortgage, income, and expenses to see whether this is a fit for your household.
- 2
A plan built around your loans
No one-size-fits-all program. We structure it around what you have now and what you qualify for.
- 3
Same dollars, faster payoff
In many cases you do not need more income or extra monthly payments. The dollars you already spend do more of the work.
Imagine the interest you stop paying becoming the fuel for your future.
Saving hundreds of thousands of dollars in interest is only half the story. Once the debt is gone, the same monthly cash flow can go toward long-term wealth building and retirement, with attention to tax consequences.
Your payoff and your future get planned together, so the money you free up keeps working for you.
Is this right for you?
It may be a good fit if you
- Own a home with a mortgage
- Have positive monthly cash flow, even a modest amount
- Can qualify for a line of credit
- Are willing to run your finances a little differently
It probably is not if you
- Spend more than you bring in each month
- Cannot qualify for any type of line of credit
- Are not comfortable with the day-to-day changes it requires
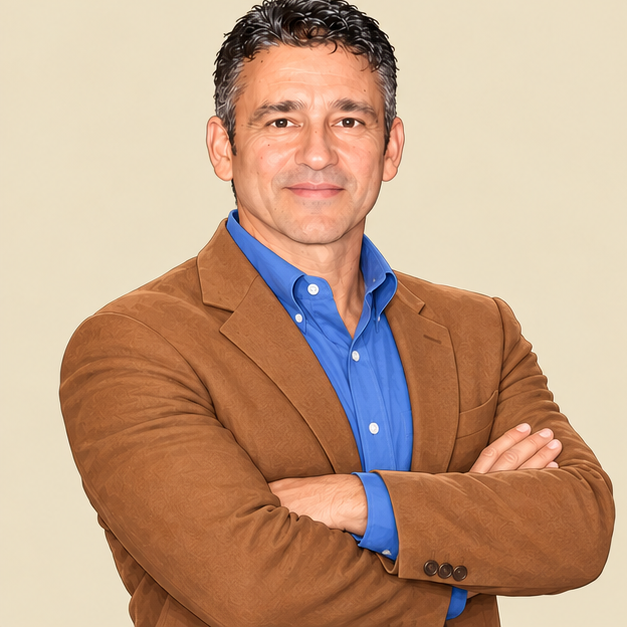
Hi, I'm Chris.
I grew up around engines, entrepreneurs, and independence. I was born in Daytona Beach, and my family has been here for at least three generations. My grandfather, Marshall Teague, known as the "King of the Beach," graduated from Seabreeze in 1939 and went on to become one of the early pioneers of modern stock car racing. I've had the honor of giving the invocation at the Motorsports Hall of Fame of America induction ceremony.
Racing teaches you that speed without control is chaos, and the same is true with money. Power without structure is dangerous, and freedom without discipline doesn't last. I grew up in Atlanta and spent my summers in Daytona Beach. I studied at the University of Georgia, earned my degree from Reformed Theological Seminary, spent years in ministry, and raised my own family in Orlando. The theme never changed: freedom. Not the emotional kind. The structural kind.
A word about my faith
My faith in Jesus Christ isn't a marketing angle. It's the foundation for how I work: stewardship over waste, integrity over shortcuts, and freedom that is built, not just hoped for. You don't have to share my beliefs to work with me. You'll get the same honesty and care either way.
Find out what your numbers could look like.
A free, no-pressure conversation. No obligation.
Try the calculatorChris Attaway is an independent affiliate of Truth In Equity. Chris Attaway and The Freedom Ledger are not a bank, a lender, or a mortgage broker, and do not make or originate loans of any kind. Strategies we discuss may involve loans or lines of credit from third-party lenders, subject to their own approval.
Results vary. Savings and payoff timelines shown reflect averages reported by Truth In Equity and are not guarantees. Lines of credit are typically variable rate, and your rate and payments can change. This site is for educational purposes only and is not tax, legal, or investment advice. Consult your own tax and legal professionals.
Real people. Real payoffs.
These are real homeowners who changed how their money moves. Different loans, different lives, same idea.
Told 19 months. Took 26. Paid it off anyway.
AC started in 2016. Then life happened: a big home remodel, a wedding, and a baby on the way. It took longer than his first projection, and his mortgage still got paid off.
Life happened. The plan held."Not for everyone." For them, it worked as described.
Jack and Linda came in careful. They'll tell you this isn't for everyone. For them, it worked the way it was explained, and they paid off their mortgage the day after Christmas in 2017.
Mortgage paid offAlready on a 15-year loan. Still did better.
Melanie thought a 15-year mortgage was the fast lane. Running her money through a line of credit turned out to be much better for her household. Her friends are still skeptical when she tells them.
Faster than a 15-yearHis business cash flow did the heavy lifting.
Lou runs his own business. Moving his business cash flow through a line of credit helped him pay off his mortgage fast. He says it works especially well for sole proprietors.
Business ownersWant to talk to someone who's been there? I can connect you with real clients whose situation looks like yours. Book a free quick chat, tell me what you're working with, and I'll make the introduction.
Real client stories. First names only, for privacy. Results vary by household and are not guaranteed. Not financial advice.